
BCBS AL’s 2027 Silver and Bronze Plans Are Here. Here’s What Changed.
Blue Cross and Blue Shield of Alabama has released its 2027 Blue Secure Silver and Blue Saver Bronze plans for business groups.
At first glance, both plans look similar to their 2026 versions. But once you dig into the details, there are several changes brokers should know before presenting renewal options to clients.
Some changes are minor. Others could have a much bigger impact on how employees actually use their coverage.
Blue Saver Bronze: Lower Deductible, Higher Out-of-Pocket Maximum
The Blue Saver Bronze plan has some of the most noticeable changes for 2027.
For 2026, the in-network individual deductible was $9,100 and the family deductible was $18,200. The in-network out-of-pocket maximum matched those same amounts. 2026 BCBS AL Blue Saver Bronze.
For 2027, the deductible drops to $8,000 for individuals and $16,000 for families. At the same time, the out-of-pocket maximum increases to $10,000 for individuals and $20,000 for families. Blue Saver Bronze for Business.
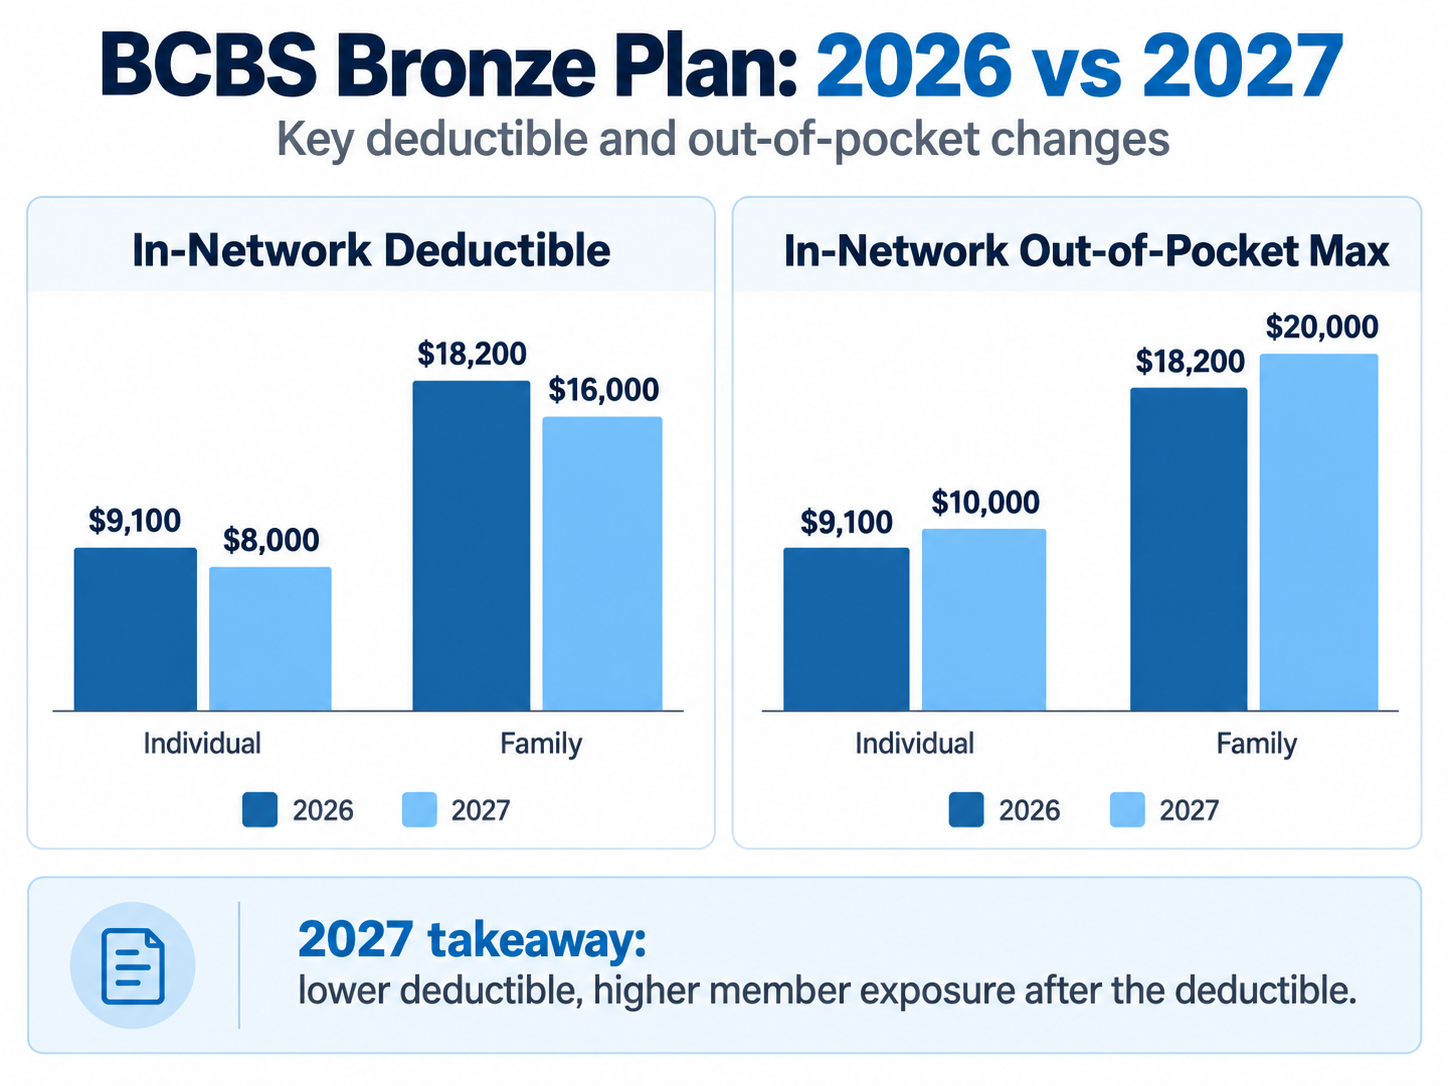
That creates an important distinction for brokers to explain. The lower deductible means members reach that threshold sooner. However, the higher out-of-pocket maximum means members can still have more total exposure over the course of the year. In other words, a lower deductible does not necessarily mean a member will spend less overall.
Bronze Prescription Coverage Also Changed
Prescription coverage is another area brokers should pay close attention to.
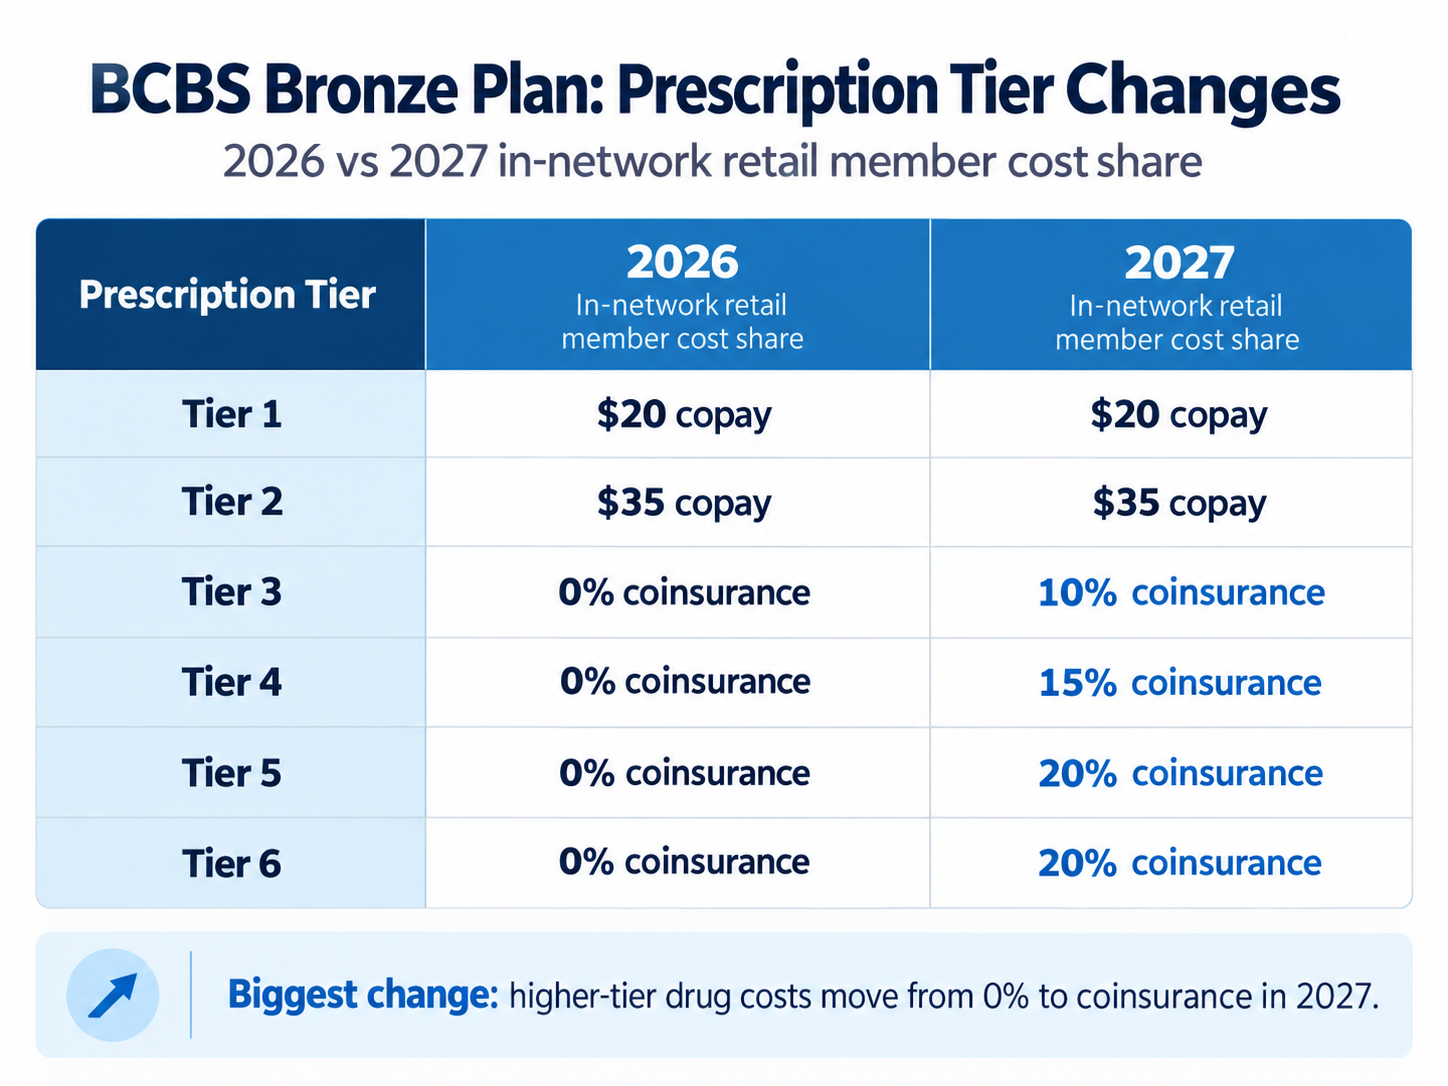
In 2026, Tier 3 through Tier 6 drugs showed 0% coinsurance for in-network retail coverage. 2026 BCBS AL Blue Saver Bronze …
For 2027, those same tiers change to:
- Tier 3: 10% coinsurance
- Tier 4: 15% coinsurance
- Tier 5: 20% coinsurance
- Tier 6: 20% coinsurance
Tier 1 and Tier 2 remain at $20 and $35 retail copays. Blue Saver Bronze for Business.
For members who regularly take higher-tier medications, this could be a meaningful change in overall cost.
In Short: Blue Saver Bronze Changes for 2027
- Lower individual deductible: $9,100 to $8,000
- Lower family deductible: $18,200 to $16,000
- Higher individual out-of-pocket maximum: $9,100 to $10,000
- Higher family out-of-pocket maximum: $18,200 to $20,000
- Higher-tier prescription costs increased: Tier 3 through Tier 6 now have 10% to 20% coinsurance
The main takeaway is simple: the Bronze deductible is lower, but the member’s total potential exposure is higher.
Blue Secure Silver: Same Deductible, Higher Maximum Exposure
The Blue Secure Silver plan changes less dramatically than Bronze, but there are still several increases worth noting.
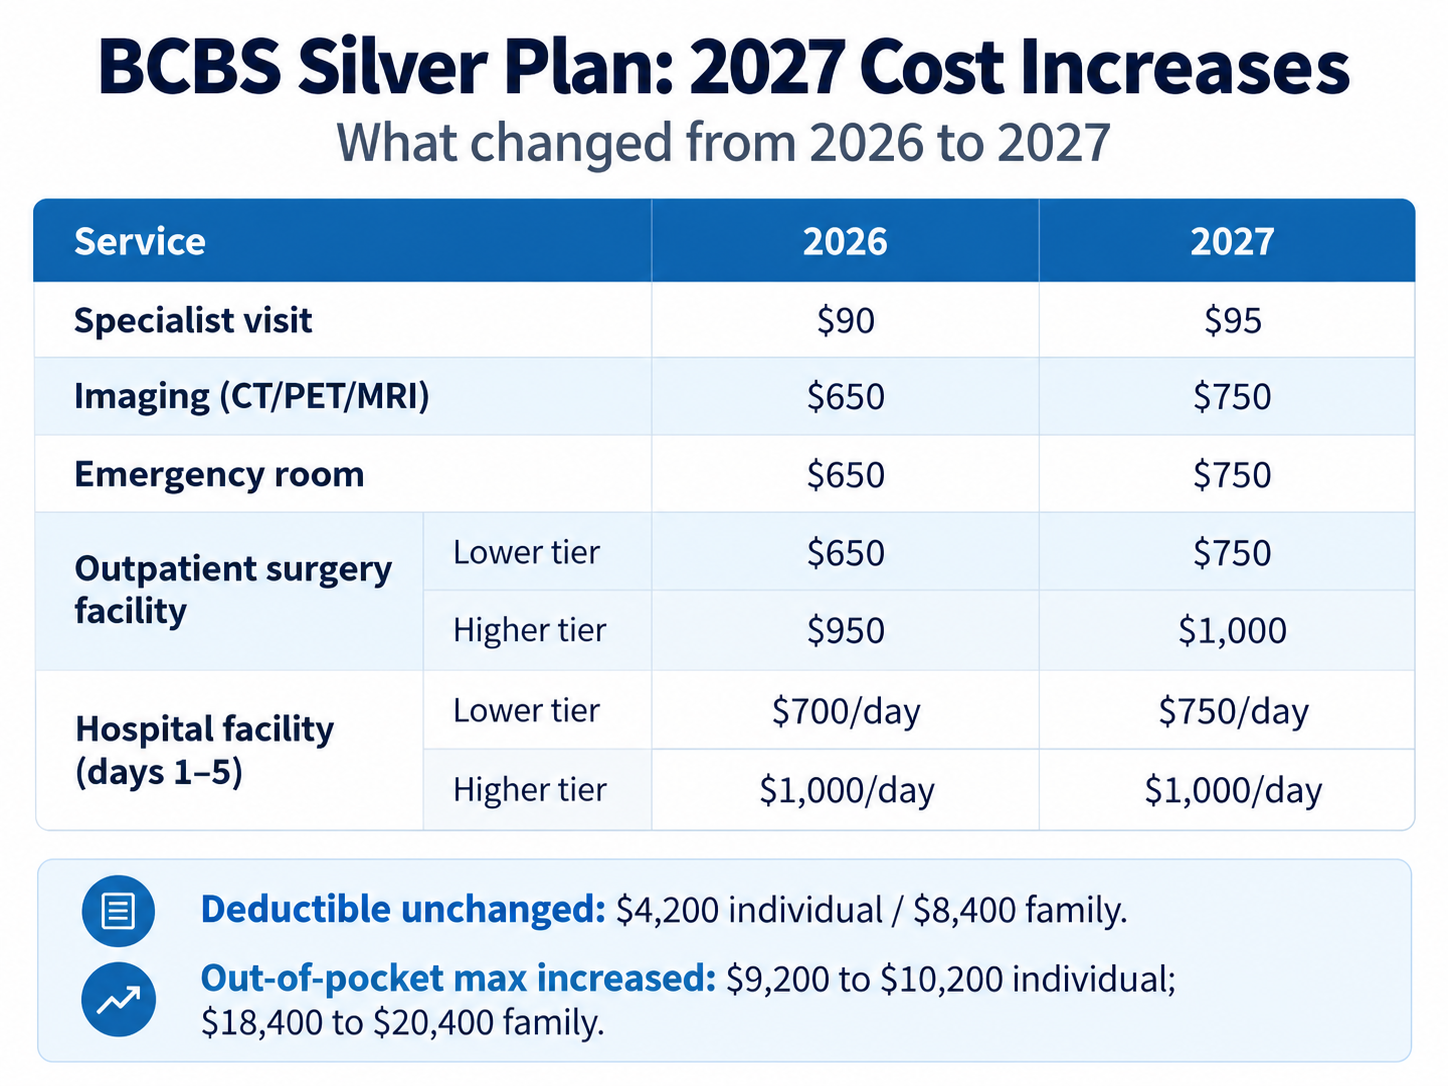
The deductible remains unchanged at $4,200 individual / $8,400 family for 2027. Blue Secure Silver for Business…
The out-of-pocket maximum, however, increases from $9,200 to $10,200 for individuals and from $18,400 to $20,400 for families. 2026 BCBS AL Secure Silver SBC Blue Secure Silver for Business…
That means the deductible stays exactly the same, but members have an additional $1,000 of potential out-of-pocket exposure per individual before reaching the plan maximum.
Several Silver Copays Are Increasing
A number of commonly used benefits also become more expensive in 2027.
The specialist visit copay increases from $90 to $95. 2026 BCBS AL Secure Silver SBC Blue Secure Silver for Business…
Imaging services such as CT scans, PET scans and MRIs increase from $650 to $750. 2026 BCBS AL Secure Silver SBC Blue Secure Silver for Business…
Emergency room visits also increase from $650 to $750. 2026 BCBS AL Secure Silver SBC Blue Secure Silver for Business…
Outpatient surgery facility copays also rise. The lower member cost share tier increases from $650 to $750 while the higher tier increases from $950 to $1,000. 2026 BCBS AL Secure Silver SBC Blue Secure Silver for Business…
Hospital facility costs also increase for the lower member cost share tier. In 2026, the cost was $700 per day for days 1 through 5. For 2027, that increases to $750 per day. The higher tier remains at $1,000 per day. 2026 BCBS AL Secure Silver SBC Blue Secure Silver for Business.
In Short: Blue Secure Silver Changes for 2027
- Deductible stays the same: $4,200 individual / $8,400 family
- Higher individual out-of-pocket maximum: $9,200 to $10,200
- Higher family out-of-pocket maximum: $18,400 to $20,400
- Higher specialist copay: $90 to $95
- Higher imaging copay: $650 to $750
- Higher ER copay: $650 to $750
- Higher outpatient surgery costs
- Higher lower-tier hospital costs
The Silver plan is less of a redesign and more of a cost-sharing increase. The deductible stays the same, but members may pay more in several common areas.
What These Changes Mean for Brokers
The biggest takeaway is that brokers should be careful about looking at the deductible alone.
The 2027 Bronze plan has a lower deductible, which may make it look more attractive at first glance. But the higher out-of-pocket maximum means members can still have more total exposure over the course of the year. The addition of coinsurance on higher prescription tiers creates another area where certain employees could see higher costs.
The Silver plan is more straightforward. The deductible stays the same, but the out-of-pocket maximum increases and several commonly used benefits become more expensive.
For brokers, this makes it even more important to compare the entire benefit structure, not just premium and deductible. A plan can look very similar on paper while still shifting more cost to employees in areas they are likely to use.
These changes may also create an opportunity to look at other strategies for controlling overall healthcare costs and employee exposure. Depending on the group, that could include alternative plan designs, dual-option strategies or secondary coverage such as GAP insurance.
At Providence Benefits, we routinely work with brokers to evaluate these types of changes and identify ways to help control costs without losing sight of the employee experience. The goal is not simply to find the lowest premium. It is to help employers understand what the plan costs, what employees may actually pay and where another strategy could make sense.
Comments (0)